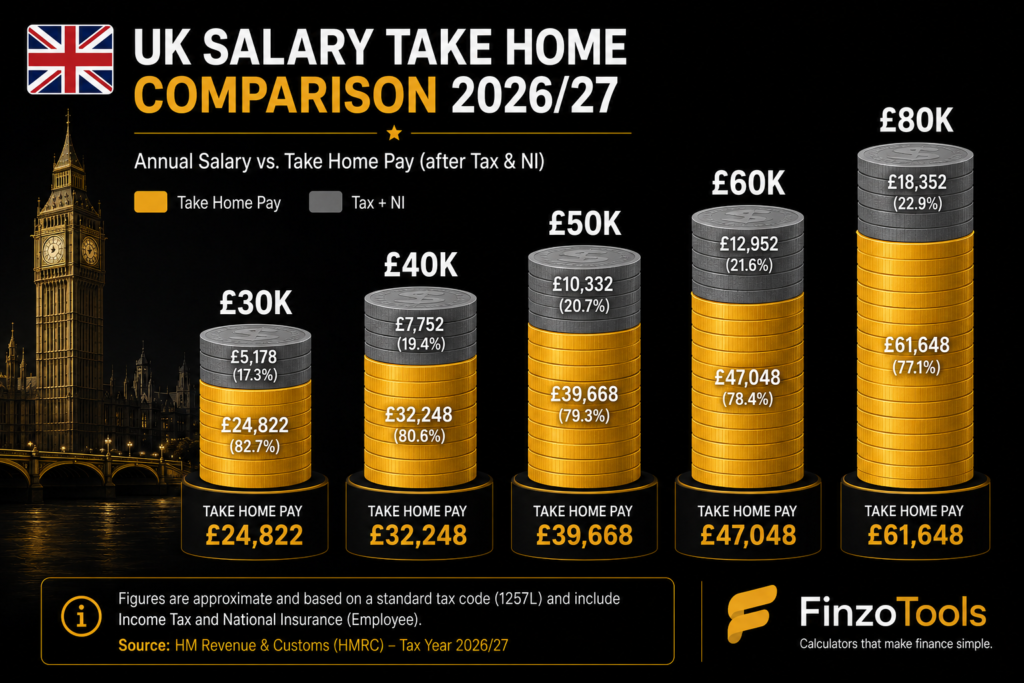
The question every UK worker asks at some point: what do I actually take home? The answer is always less than you expect. On a £40,000 salary in 2026/27, you keep £32,320 — meaning £7,680 goes to income tax and National Insurance before your pay even reaches your bank account. Add a workplace pension and student loan, and the gap between gross and net widens further.
This guide breaks down the exact take-home pay at common UK salary levels from £25,000 to £100,000 — showing income tax, National Insurance, and the combined effective deduction rate. No assumptions about pension or student loans unless stated, so you can see the pure tax picture first.
UK Tax Rates and Thresholds 2026/27
Before the salary breakdowns, here are the key numbers. The personal allowance, tax bands, and NI thresholds are all frozen until April 2031 — extended in the Autumn Budget 2025. This freeze is the single biggest silent tax increase for UK workers, dragging more income into higher bands each year as wages rise with inflation.
| Component | 2026/27 Rate |
|---|---|
| Personal Allowance | £12,570 |
| Basic Rate (20%) | £12,571 – £50,270 |
| Higher Rate (40%) | £50,271 – £125,140 |
| Additional Rate (45%) | Above £125,140 |
| Employee NI (8%) | £12,571 – £50,270 |
| Employee NI (2%) | Above £50,270 |
The personal allowance starts tapering at £100,000 of income, reducing by £1 for every £2 above that threshold. By £125,140, the personal allowance is completely eliminated, creating an effective marginal rate of 60% in the £100,000–£125,140 band (40% tax + 20% allowance withdrawal).
Take Home Pay at Every Salary Level
The following table shows annual and monthly take-home pay after income tax and National Insurance only. No pension or student loan deductions are included — those are covered separately below.
| Gross Salary | Income Tax | National Insurance | Annual Take Home | Monthly Take Home |
|---|---|---|---|---|
| £25,000 | £2,486 | £994 | £21,520 | £1,793 |
| £30,000 | £3,486 | £1,394 | £25,120 | £2,093 |
| £35,000 | £4,486 | £1,794 | £28,720 | £2,393 |
| £40,000 | £5,486 | £2,194 | £32,320 | £2,693 |
| £45,000 | £6,486 | £2,594 | £35,920 | £2,993 |
| £50,000 | £7,486 | £2,994 | £39,520 | £3,293 |
| £60,000 | £11,432 | £3,211 | £45,357 | £3,780 |
| £70,000 | £15,432 | £3,411 | £51,157 | £4,263 |
| £80,000 | £19,432 | £3,611 | £56,957 | £4,746 |
| £100,000 | £27,432 | £4,011 | £68,557 | £5,713 |
The most noticeable jump is between £50,000 and £60,000. An extra £10,000 of gross salary only delivers £5,837 in additional take-home pay — the higher rate of 40% tax plus 2% NI takes 42p from every additional pound. By contrast, the £30,000-to-£40,000 jump delivers £7,200 of additional take-home on the same £10,000 increase, because the entire amount stays within the basic rate band.
Take Home Pay on a 40K Salary After Tax
A £40,000 salary is one of the most commonly searched salary levels in the UK — and for good reason. It sits firmly within the basic rate band, meaning every pound is taxed at just 20% income tax and 8% National Insurance. No higher-rate complications, no allowance tapers, no surprises.
On £40,000, your take-home pay breaks down as follows: the first £12,570 is tax-free (your personal allowance), the remaining £27,430 is taxed at 20% (£5,486), and National Insurance at 8% takes another £2,194. Your annual take-home is £32,320, which works out to £2,693 per month, £622 per week, or approximately £124 per working day.
If you have a Plan 2 student loan, deduct another £1,143 per year (9% above £27,295), bringing monthly take-home to £2,598. With a 5% pension contribution on top, your monthly take-home drops to approximately £2,498 — but you gain £2,000 in your pension pot plus employer contributions.
Weekly and Daily Take Home Pay
| Gross Salary | Monthly | Weekly | Per Working Day |
|---|---|---|---|
| £25,000 | £1,793 | £414 | £83 |
| £30,000 | £2,093 | £483 | £97 |
| £40,000 | £2,693 | £622 | £124 |
| £50,000 | £3,293 | £760 | £152 |
| £60,000 | £3,780 | £872 | £174 |
| £80,000 | £4,746 | £1,095 | £219 |
| £100,000 | £5,713 | £1,318 | £264 |
Effective Tax Rates: What You Really Pay
| Salary | Marginal Rate | Effective Tax Rate | Effective Tax + NI | You Keep |
|---|---|---|---|---|
| £25,000 | 28% (20+8) | 9.9% | 13.9% | 86.1% |
| £30,000 | 28% (20+8) | 11.6% | 16.3% | 83.7% |
| £40,000 | 28% (20+8) | 13.7% | 19.2% | 80.8% |
| £50,000 | 28% (20+8) | 15.0% | 21.0% | 79.0% |
| £60,000 | 42% (40+2) | 19.1% | 24.4% | 75.6% |
| £80,000 | 42% (40+2) | 24.3% | 28.8% | 71.2% |
| £100,000 | 42% (40+2) | 27.4% | 31.4% | 68.6% |
The effective rate tells the real story. On £30,000, you pay 16.3% of your total salary in combined tax and NI. On £40,000, it is 19.2% — meaning you keep just over 80p from every pound earned. On £80,000, the effective rate rises to 28.8%. The progressive system means that even at £80,000, you are not paying 42% on everything — just on the portion above £50,270.
The Impact of Workplace Pension
Under auto-enrolment, most UK employees contribute a minimum of 5% of qualifying earnings to a workplace pension, with the employer adding at least 3%. If your pension uses a net pay arrangement (the most common for larger employers), your contribution is deducted before tax is calculated, reducing your taxable income. If it uses a relief at source arrangement, you pay from after-tax income and HMRC adds 20% tax relief.
Here is how a 5% employee pension contribution affects take-home pay under a net pay arrangement:
| Salary | Pension (5%) | Take Home (no pension) | Take Home (with pension) | True Cost of Pension |
|---|---|---|---|---|
| £30,000 | £1,500 | £25,120 | £23,900 | £1,220 (saves £280 tax) |
| £40,000 | £2,000 | £32,320 | £30,760 | £1,560 (saves £440 tax) |
| £50,000 | £2,500 | £39,520 | £37,320 | £2,200 (saves £300 tax) |
| £80,000 | £4,000 | £56,957 | £53,437 | £3,520 (saves £480 tax) |
The “true cost” column shows what your pension actually costs in take-home pay. On £40,000, a £2,000 pension contribution only reduces your take-home by £1,560 because you save £440 in combined tax and NI relief. For higher-rate taxpayers, the tax saving is even greater — making pension contributions one of the most tax-efficient things you can do with your salary.
Student Loan Repayments
If you have a student loan, repayments are deducted through PAYE once your income exceeds the plan threshold. The main plans for 2026/27 are:
| Plan | Threshold | Rate | Repayment on £40K |
|---|---|---|---|
| Plan 1 (pre-2012) | £24,990 | 9% | £1,351 |
| Plan 2 (post-2012) | £27,295 | 9% | £1,143 |
| Plan 5 (post-2023) | £25,000 | 9% | £1,350 |
On a £40,000 salary with a Plan 2 loan, the annual student loan repayment is approximately £1,143 — or £95 per month. Combined with tax and NI, total deductions rise to £8,823, leaving take-home pay of £31,177 per year (£2,598 per month).
The £50,270 Cliff Edge
The transition from basic rate to higher rate at £50,270 is the most impactful threshold in the UK tax system. Below £50,270, every additional pound costs you 28p in combined tax and NI (20% + 8%). Above it, every additional pound costs you 42p (40% + 2%). That is a 50% increase in the marginal rate.