Last verified: September 2026 — Source: Revenue Commissioners, Citizens Information, Budget 2026
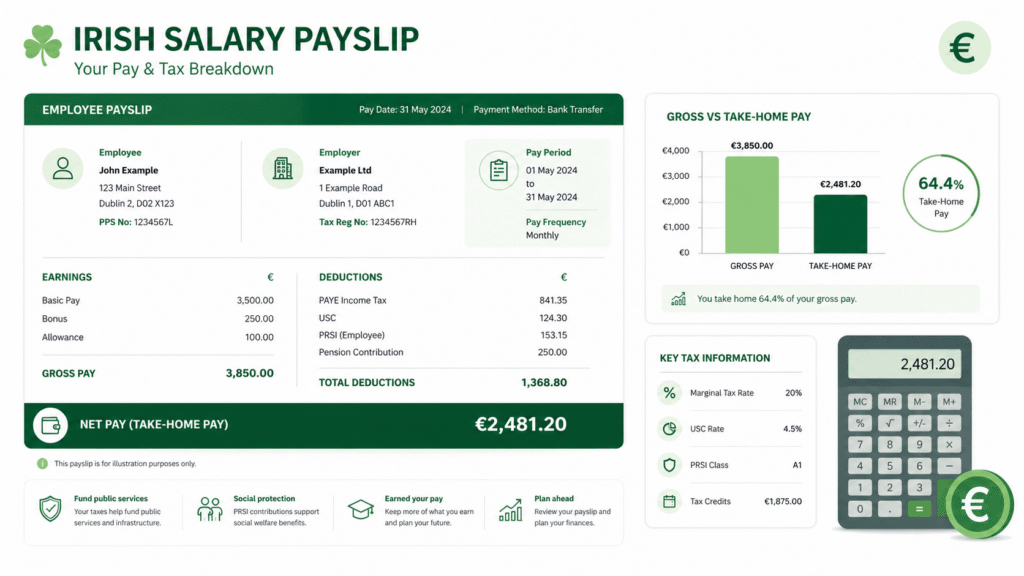
Ireland’s payslip is unusually complicated. Three separate deductions — income tax through PAYE, the Universal Social Charge, and PRSI social insurance — each with their own thresholds, rates, and exemptions. Most people know their gross salary but have only a vague idea of where the rest goes.
This guide breaks down exactly what you keep at every salary level from €30,000 to €100,000, explains how each deduction is calculated step by step, and shows how pension contributions and tax credits can meaningfully change the picture.
The Three Deductions on Every Irish Payslip
1. PAYE Income Tax — The Biggest Deduction
Ireland has two income tax rates: 20% on income up to the standard rate band (€42,000 for a single person in 2026) and 40% on everything above that threshold.
Your tax bill is then reduced by tax credits — the main ones being the Personal Tax Credit (€1,875) and the PAYE Employee Tax Credit (€1,875), giving most PAYE workers €3,750 in total credits. Credits reduce your tax bill directly, not your taxable income — an important distinction.
For a single person earning €50,000: first €42,000 taxed at 20% = €8,400, remaining €8,000 taxed at 40% = €3,200, gross tax = €11,600, less credits (€3,750) = €7,850 PAYE payable.
Married couples with one earner get a higher standard rate band of €51,000. Two-earner couples can transfer up to €33,000 of the band between them, which often reduces the total household tax bill.
2. Universal Social Charge (USC) — The Charge With No Credits
USC applies to gross income with almost no deductions or credits available to offset it:
| Income Band | USC Rate 2026 |
|---|---|
| First €12,012 | 0.5% |
| €12,013 – €28,700 | 2% |
| €28,701 – €70,044 | 3% |
| Above €70,044 | 8% |
If your total income is under €13,000, you are fully exempt from USC. Medical card holders with income under €60,000 pay reduced rates. Occupational pension contributions are deducted before USC is calculated — reducing your USC bill. For a full breakdown, see our Ireland USC Rates & Bands 2026 guide.
3. PRSI — Social Insurance With No Upper Limit
Employee PRSI (Class A) is 4% of gross earnings. Unlike UK National Insurance, there is no upper earnings limit — PRSI is charged on all income without cap. Workers earning under €352/week are exempt entirely.
PRSI funds the State Pension (Contributory), Jobseeker’s Benefit, Maternity Benefit, Illness Benefit, and several other social welfare payments. Your PRSI contributions directly affect your future State Pension entitlement — you need 520 paid contributions (10 years) to qualify for the full contributory pension. Read our guide: PRSI Contributions for Irish Pension 2026.
Take-Home Pay at Every Salary Level — €30K to €100K
Here is what a single PAYE worker with standard tax credits takes home at each salary level in 2026:
| Gross Salary | PAYE | USC | PRSI | Annual Take-Home | Monthly Take-Home | Effective Rate |
|---|---|---|---|---|---|---|
| €30,000 | €2,250 | €433 | €1,200 | €26,117 | €2,176 | 12.9% |
| €35,000 | €3,250 | €583 | €1,400 | €29,767 | €2,481 | 14.9% |
| €40,000 | €4,250 | €733 | €1,600 | €33,417 | €2,785 | 16.5% |
| €45,000 | €5,850 | €883 | €1,800 | €36,467 | €3,039 | 19.0% |
| €50,000 | €7,850 | €1,033 | €2,000 | €39,117 | €3,260 | 21.8% |
| €60,000 | €11,850 | €1,333 | €2,400 | €44,417 | €3,701 | 26.0% |
| €70,000 | €15,850 | €1,633 | €2,800 | €49,717 | €4,143 | 29.0% |
| €80,000 | €19,850 | €2,431 | €3,200 | €54,519 | €4,543 | 31.9% |
| €100,000 | €27,850 | €4,031 | €4,000 | €64,119 | €5,343 | 35.9% |
Figures assume a single PAYE worker with standard tax credits (Personal €1,875 + PAYE €1,875 = €3,750) and standard rate band of €42,000.
The biggest marginal rate jump happens between €42,000 and €43,000 — that is where the 40% income tax rate kicks in. Above €70,044, the top USC rate of 8% also kicks in, bringing the combined marginal rate to 52% (40% PAYE + 8% USC + 4% PRSI) — one of the highest marginal rates in Europe.
Take-Home Pay on €40,000 Salary in Ireland
€40,000 is one of the most commonly searched salary levels in Ireland — and the good news is that it sits entirely within the 20% standard rate band. No 40% tax applies at all.
On €40,000, your annual deductions are: PAYE €4,250, USC €733, and PRSI €1,600 — total deductions €6,583. Your take-home pay is €33,417 per year or €2,785 per month or €643 per week. Your effective tax rate is just 16.5%.
Add a Plan 2 pension at 10% (€4,000) and your take-home drops to approximately €2,518 per month — but you save €800 in income tax relief and build €4,000 towards retirement.
Take-Home Pay on €50,000 Salary in Ireland
At €50,000, you cross into the higher rate band. The first €42,000 is taxed at 20%, but the remaining €8,000 is taxed at 40% — costing an extra €1,600 compared to if the 20% rate applied to everything.
Your annual take-home is €39,117 or €3,260 per month or €752 per week. The effective rate jumps to 21.8% — a significant step up from the 16.5% at €40,000.
Weekly Take-Home Pay in Ireland
| Gross Salary | Monthly | Fortnightly | Weekly |
|---|---|---|---|
| €30,000 | €2,176 | €1,004 | €502 |
| €40,000 | €2,785 | €1,285 | €643 |
| €50,000 | €3,260 | €1,505 | €752 |
| €60,000 | €3,701 | €1,708 | €854 |
| €70,000 | €4,143 | €1,912 | €956 |
| €100,000 | €5,343 | €2,466 | €1,233 |
How Pension Contributions Reduce Your Tax in Ireland
Pension contributions are the most tax-efficient savings vehicle available to Irish PAYE workers. You get income tax relief at your marginal rate — 40% for higher-rate taxpayers, 20% for standard-rate taxpayers. Occupational pension contributions also reduce your USC liability. The income tax saving alone is substantial.
| Salary | 10% Pension | Tax Saved | Real Cost to You | Monthly Impact |
|---|---|---|---|---|
| €40,000 | €4,000 | €800 (at 20%) | €3,200 | −€267 |
| €50,000 | €5,000 | €2,000 (at 40%) | €3,000 | −€250 |
| €70,000 | €7,000 | €2,800 (at 40%) | €4,200 | −€350 |
For a 40% taxpayer, every €100 contributed to a pension costs only €60 out of pocket. The age-based contribution limits determine the maximum you can contribute with tax relief: under 30 = 15%, 30–39 = 20%, 40–49 = 25%, 50–54 = 30%, 55–59 = 35%, 60+ = 40% of earnings (capped at €115,000). Full guide: PRSA Pension Ireland 2026 — Contributions, Tax Relief & How It Works.
Tax Credits That Increase Your Take-Home
Beyond the standard Personal (€1,875) and PAYE (€1,875) credits, check whether you qualify for any of these additional credits that directly reduce your tax bill:
Home Carer Tax Credit: €1,800 — available if your spouse/partner works in the home caring for a dependent person.
Single Person Child Carer Credit: €1,750 — for the primary carer of a qualifying child.
Rent Tax Credit: €750 per person (€1,500 for couples) — if you are renting your home.
Medical Expenses Relief: 20% of qualifying medical expenses not covered by insurance or the Drug Payment Scheme.
Flat Rate Expenses: Varies by profession — Revenue allows workers in certain trades and professions to claim a standard deduction for work-related expenses without receipts.
Each credit reduces your tax bill directly. A €1,000 credit saves you €1,000 in tax regardless of your income level — unlike a deduction, which saves you 20% or 40% of the amount depending on your marginal rate.
The 52% Marginal Rate Trap — And How to Avoid It
Once your income exceeds €70,044, every additional euro earned is taxed at a combined 52%: 40% income tax + 8% USC + 4% PRSI. This is one of the highest marginal rates in Europe and it starts at a relatively modest income level by European standards.
The most effective way to reduce your exposure to the 52% rate is pension contributions. Every euro contributed above the standard rate band saves you 40% income tax immediately. For a worker earning €80,000, maximising pension contributions within the age-based limit can reduce the effective tax rate from 31.9% to approximately 26%.
Other strategies include salary sacrifice for pension, making full use of all available tax credits, and — for married couples — optimising the transfer of standard rate bands between spouses.
Married vs Single — How Marriage Changes Your Take-Home
One-earner couple: Standard rate band increases to €51,000 (from €42,000). If one spouse earns €60,000 and the other has no income, the couple pays tax as if €51,000 is taxed at 20% and only €9,000 at 40% — saving approximately €3,600/year compared to a single person on the same salary.
Two-earner couple: Combined standard rate band of up to €84,000 (€42,000 each, with up to €33,000 transferable). This flexibility allows couples to minimise the amount of income taxed at 40%.
Home Carer Credit: €1,800 additional credit if one spouse works in the home — direct €1,800 tax saving.
Ireland vs UK Tax: How They Compare
Many professionals compare Irish and UK tax when considering job offers across the two countries. On a €50,000 salary (approximately £43,000), an Irish worker takes home about €39,117 (effective rate 21.8%) while a UK worker on the equivalent salary takes home approximately £35,920 (effective rate 17.4% including NI). Ireland’s USC adds a layer that the UK does not have, but Ireland’s tax credits are more generous for families. For a full comparison, see our Ireland vs UK Tax Comparison 2026.
Calculate Your Exact Irish Take-Home Pay
The FinzoTools Ireland Salary Calculator applies all PAYE bands, USC rates, PRSI, tax credits, and pension relief to show your exact take-home pay. Enter your gross salary to see annual, monthly, and weekly breakdowns with every deduction itemised.
Related Guides
Ireland USC Rates & Bands 2026 — full USC breakdown with worked examples
PRSI Contributions for Irish Pension 2026 — how PRSI affects your State Pension
PRSA Pension Ireland 2026 — contributions, tax relief & how it works
Ireland Stamp Duty Rates 2026 — rates for property purchases
Ireland vs UK Tax Comparison 2026
Source: All rates verified against Revenue Commissioners tax charts, Citizens Information, and Budget 2026 Summary, September 2026.